Net worth sounds like a term for wealthy people, which is exactly why most people never calculate theirs. In reality it is the simplest number in personal finance: what you own minus what you owe. This guide turns it into a 30-minute calculation workshop — what counts, what does not, two worked examples, and the habit that makes the number useful over time. No expertise required, and no judgment attached to the result.
Net Worth in One Sentence
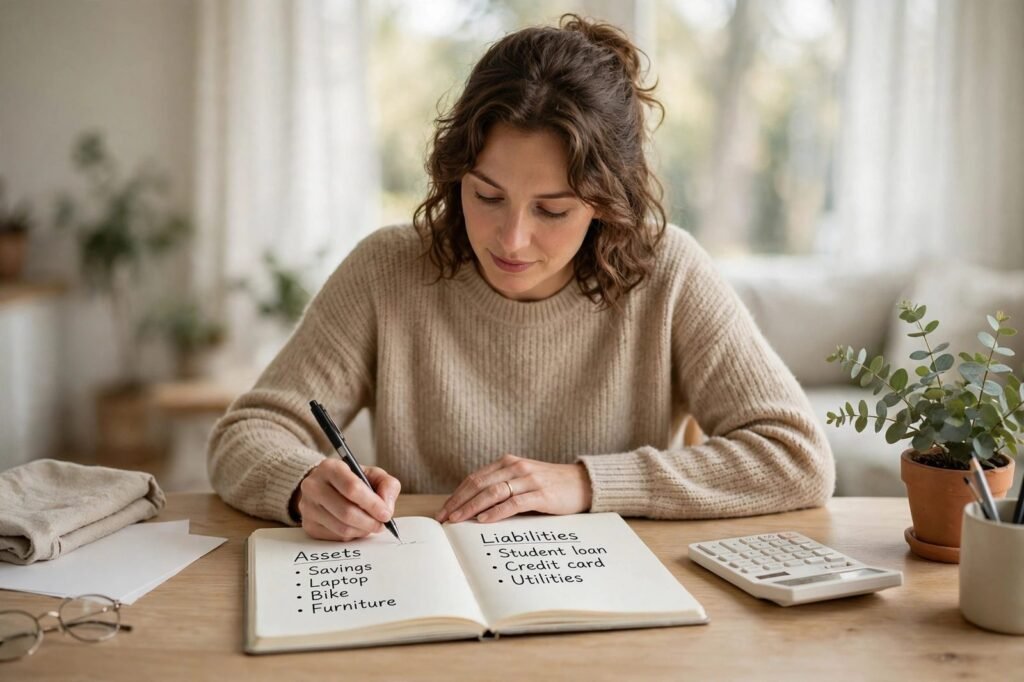
Your net worth is your assets minus your liabilities. Assets are what you own; liabilities are what you owe. If your assets are larger, your net worth is positive. If your liabilities are larger, it is negative. That is the whole definition, and everything else in this guide is about applying it honestly.
The US Securities and Exchange Commission’s investor education site frames it the same way: take an honest look at what you own and what you owe — this is a “net worth statement.” List assets on one side and liabilities (debts) on the other, then subtract liabilities from assets. See Investor.gov: Figure Out Your Finances for that framing and for the annual-update habit below.
What Counts — and What Doesn’t
Assets include: cash and bank balances, savings and investments, retirement accounts, the market value of your home, vehicles, and any other property you could sell. Liabilities include: mortgages, car loans, student loans, credit card balances, personal loans, and any other money you owe.
The tricky cases deserve a decision, not a guess. Your home counts as an asset at its approximate market value, and your mortgage counts as a liability for the full remaining balance — so what matters is the equity, the difference between the two. Your car counts at what it would sell for today, not what you paid for it. Your pension counts if you can put a value on it, but treat it as a long-term asset, not money available now. Household items — furniture, clothes, electronics — technically count, but their resale value is usually so low that including them adds clutter, not clarity. Leave them out unless they are genuinely valuable.
Two Worked Examples
Every figure below is an illustration, not real data — the method is the point, not the numbers.
Example one: an early-career renter. Maya rents, so she has no home or mortgage. Her assets are: bank balance 2,000, savings 3,000, and a retirement account worth 8,000 — total 13,000. Her liabilities are: a student loan of 18,000 and a credit card balance of 1,500 — total 19,500. Her net worth is 13,000 minus 19,500: negative 6,500. That negative number is normal for someone early in their career, and it is a starting point, not a verdict.
Example two: a mid-career homeowner. Daniel owns a home worth 280,000 in this illustration, with a mortgage balance of 190,000 — equity of 90,000. His other assets are: savings 12,000, investments 25,000, retirement 60,000, and a car worth 9,000 — total assets 386,000. His liabilities are the mortgage 190,000, a car loan 6,000, and a credit card balance 2,000 — total 198,000. His net worth is 386,000 minus 198,000: positive 188,000. A large part of it is home equity, which leads to the next distinction.
Liquid Net Worth vs Total Net Worth
Total net worth includes everything, including your home. Liquid net worth includes only what you can turn into cash quickly: bank balances, savings, and investments you can sell without a major process. Daniel’s total net worth is 188,000, but his liquid net worth is roughly 97,000 — and if he needed money in an emergency, only the liquid part would help quickly. That is why the distinction matters: a high total net worth with almost no liquid assets still leaves you vulnerable to a sudden bill.
The liquid layer is where your emergency savings live, which is why the two ideas belong together. Our guide to the emergency fund covers how much liquid buffer to hold and where to keep it. And the growth side of the equation — how invested assets increase over time — is explained in our guide to compound interest.
Negative Net Worth? What to Do Next
If your number is negative, do not panic — and do not ignore it either. Investor.gov’s advice is reassuring on this point: do not be discouraged by a negative net worth, because following a financial plan will help turn it into positive net worth over time. The plan is straightforward: stop the number falling further (no new high-interest debt), then raise it steadily (pay down the most expensive liabilities first, and save regularly, even in small amounts).
One warning: do not try to fix a negative number quickly with risky investments or new borrowing. A negative net worth is repaired by steady progress — paying down expensive debt and saving regularly — not by a single bold bet, which usually makes the number worse. Judge the plan over two or three annual re-measures, not on any single year’s number: the direction of travel across those years is the evidence, not one figure.
Then build the habit that makes net worth useful: update the statement every year. Investor.gov recommends exactly that — an annual update. Once a year, re-list your assets and liabilities, recalculate, and compare with last year’s number. The year-on-year change is the real measure of progress, far more meaningful than any single figure. And if your goals need structure, that annual number is the perfect progress metric for the goals system in our guide to setting financial goals.
Frequently Asked Questions
What is net worth, exactly? What you own minus what you owe. Assets on one side, liabilities on the other; subtract the second from the first.
Does my house count? What about my car or pension? Your home counts at market value, with the mortgage as a liability — the equity is what matters. Your car counts at resale value. Your pension counts as a long-term asset, but not as liquid money.
What if my net worth is negative — is that bad? It is common, especially early in a career or after taking on a mortgage or student loan. It is a starting point: follow a plan — stop adding expensive debt, pay liabilities down, save regularly — and it turns positive over time.
Does everything I own count? In theory yes, but in practice only things with meaningful resale value are worth listing. Household items usually add clutter, not clarity.
How often should I recalculate it? Once a year. An annual update shows your direction of travel, which matters more than any single number.
This article is for educational purposes only and is not financial advice. Your net worth should be calculated from your own actual assets and liabilities.