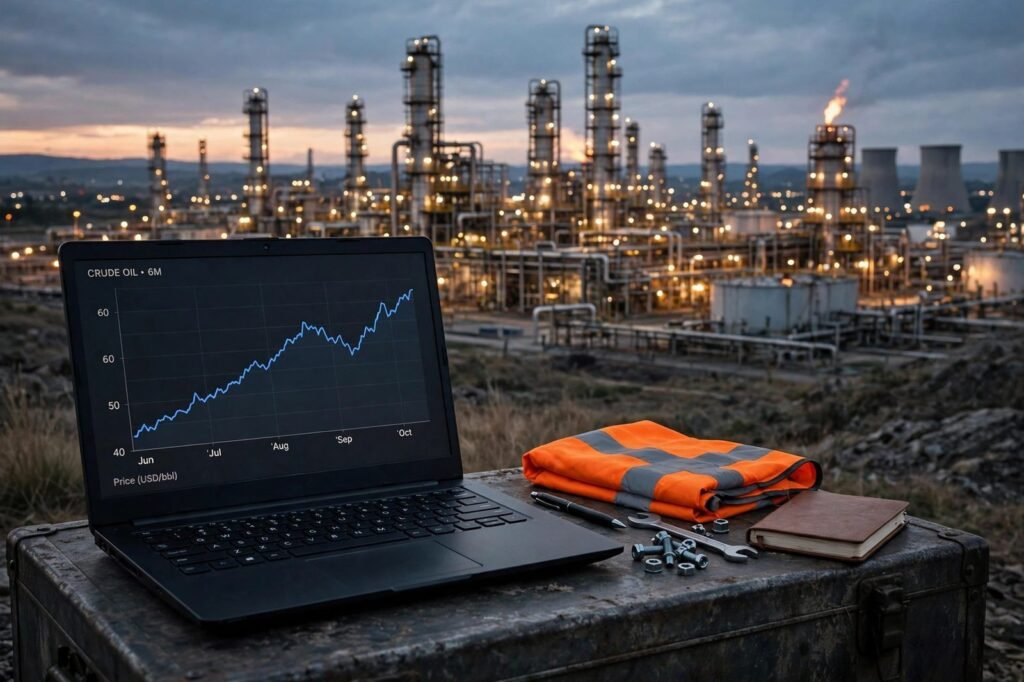
A Crude ETF promises something that sounds simple: a way to invest in oil without purchasing a barrel, renting a tanker or trading yourself in the future. Then check the price, and the fund will drop while the main oil price has remained flat, or rose much less than oil. The gap isn’t a fault. There is an entire story about how Crude ETF works.
One factor causes the lack of understanding: Crude ETF does not contain oil. There are futures contracts about oil, and these contracts expire. Everything else follows from that.
What a Crude ETF Holds
A Crude ETF holds futures contracts, not a drum. Goods such as crude oil are virtually impossible for the average person or institution to keep physical, so ETFs turn to the futures market instead. A Futures contract is a contract for the purchase or sale of oil, which represents a fixed value in the future period.
The delivery of 1,000 barrels per contract would be either awarded or awarded by a holder on the expiry of the agreement, which is exactly why ETFs would never contract before the contract expires. They sell the term of the contract, and buy the next one, and that switch’s called a roll.
The future Finwrise guide will cover platinum ETFs which can keep the physical metal in the vault. Raw oil does not have such an option for a fund, so the futures route is the only route, and the roll is unavoidable.
The Three Sources of Return
A futures based Crude ETF will receive its return from three sources. The first is spot price, which is the direction of the price of oil itself. The second is the roll yield, which is the profit or losses of current contracts, and it may help or hurt. The third is interest income: futures borrow, so the fund invests money unrelated to contracts in secure short-term securities such as Treasury accounts and that interest is more important when the stakes are higher.
Most investors only observe the first source and ignore two other ones. And so they’re surprised at the gap. The spot price can go up if the roll yield drags the fund down. The fund can end up less a month, although oil ended up a month higher.
Contango and Backwardation in Plain Language
The futures market values oil for deliveries in various months, and these prices create a curve. If the price is higher for each later month than the month before, the market is in Contango. If the price for every later month is lower, then the other way around.
Contango’s selling its share low and buying it high. The fund that sells contracts ends at the lower price of the near month and buys the following month at the higher price, so it ends with holding a little less contracts for the same money. Backwards, the roll works in reverse: the fund sells high and buys low ending with slightly more contracts, which gives support.
A front-month strategy that always holds the nearest contract, sees returns fall in contango and increase backwardness. Some funds deliberately purchase different contracts to manage Contango, with different complexity and success, so read the prospectus to get to know what a certain fund is actually doing.
Why the Gap Grows Over Months
The roll cost appears to be small in a single month and big in a year. Take an example from Fidelity’s own guide: front-month rough contracts at 100 dollars a barrel rolled in the second month contracts at 101 dollars will buy nearly 1 percent less rough, which is a loss on the reel alone. A 1 percent monthly cost annualises to almost 13 percent, sufficient to make spot-price gains or losses worse.
An earlier illustration from ETF.com from the 2020 era has a stronger impact at the same point: front-month crude with $30, which will roll up to $31 next month, means buying 3 percent fewer contracts, and 3 percent monthly cost connections to almost 40 percent per year. These are illustrations of these pages instead of the present cost, and the shape of the curve changes over time. No article can tell you about the current state of the oil curve when it continually moves.
Therefore, a flat oil price could still signify a decrease in ETF. In case oil ended in the year it started but the market spent a year in contango, the fund was paid monthly roll cost and ended a year less. – Thank you. The longer you stay, the more rolls you pay.
Futures ETFs vs Oil-Stock ETFs vs Leveraged ETFs
All three products sound alike and are not. The Futures Crude ETF follows the future of oil and carries a risk of roll-out. Oil shares in an ETF are stored in oil companies, which enable them to track corporate profits, dividends, management decisions, and prices.
A leveraged oil ETF strives for a multiple of day-to-day movement in oil, and reset each day, providing a short-term trading tool, not a long-term holding. Don’t hold a borrowed product for months, expecting the product to behave like oil.
Another warning about an earlier product: Oil exchange-traded notes traced futures oil prices without keeping the contracts, which protected them from roll effects but most oil ETNs had closed by the time of a 2023 update to the ETF.com guide. Do not count on ETNs as a live alternative without checking it beforehand.
Who a Crude ETF Suits
A crude ETF corresponds to an oil short-term look and is not a buy-and-hold proxy for the spot price. If your thesis meant oil expansion in the coming weeks, then ETFs future of the ETF would make this point. If your thesis is that oil in five years will be higher, roll cost is a strong headwind on five years and you must have some thoughts before using this tool to do this job.
Read the prospectus for two things before you buy: what the fund holds and how it rolls. Both these facts determine most of what the fund will do.
Frequently Asked Questions
What’s a Crude ETF and what’s it holding?
This is the exchange-traded fund which considers future contracts to be crude oil rather than private drums, and it holds them before their expiry.
Why isn’t a Crude ETF tracking the oil’s spot price?
The yield comes from three sources: spot price, the rolling return and the interest income. In Contango roll cost goes back below spot price.
What is Contango and backwardness, and what do they do to get back?
Later months cost more, so rolls sell low and buy high, what hurts comes back in Contango. Backward, later months cost less so rolling buys more contracts that help out returns.
A Crude ETF is a good long-term hold?
Generally no. The roll cost connections are for months, meaning futures ETFs work better than short-term tools than long-term Spot Proxies.
What is the difference between a futures ETF, an oil-stock ETF, and a leveraged ETF?
A Futures ETF follows oil contracts and runs roll risk, and an oil company has been tracked by oil-stock ETF. A leveraged ETF reset every day and was designed for days, not months.
This Article is solely for education purposes and is not investment advice. Futures-based funds are responsible for the roll risk and leverage risk that can lead to losses even if commodity prices rise, so talk to a qualified expert about your own situation before you invest.